Profit tells you whether a business model is working over time, but cash determines whether the business can pay next week’s bills. A profitable company can still face a crisis if customers pay slowly, inventory absorbs funds, or several annual expenses arrive together. A rolling 13-week cash flow forecast turns those timing risks into visible decisions.
Thirteen weeks is long enough to reveal quarterly pressure and short enough to estimate with practical detail. The forecast is not a prediction carved in stone. It is a weekly management tool that should improve as new information arrives.
Start with available cash
Use the cash that is genuinely available at the beginning of week one. Reconcile bank accounts first and separate restricted funds, customer deposits that cannot be used yet, or reserves you have committed to a specific purpose. If the business has an approved credit facility, show it separately rather than treating undrawn borrowing as cash.
This opening balance anchors the entire forecast. A small error here flows through all thirteen weeks, so assign one person to confirm the number on the same day each week.
List expected cash inflows
Begin with open invoices. Estimate when each customer is likely to pay based on the due date and actual payment behavior. A customer who usually pays ten days late should not appear as an on-time receipt merely because the invoice says “Net 30.” Include scheduled deposits, recurring revenue, cash sales, tax refunds, asset sales, and confirmed financing where relevant.
Separate high-confidence receipts from uncertain opportunities. An unsigned proposal or hoped-for sale can be shown as a scenario, but it should not fund committed payroll in the base forecast.
Map cash outflows by week
List every expected payment: payroll, contractor costs, rent, suppliers, taxes, loan payments, insurance, software, marketing, owner draws, and capital purchases. Use actual payment dates rather than averaging a monthly expense across four weeks. Timing is the reason the forecast exists.
Group expenses into useful categories and identify which are fixed, variable, or discretionary. Also flag payments that can be negotiated or rescheduled. Do not omit small recurring charges; together they can create a meaningful gap.
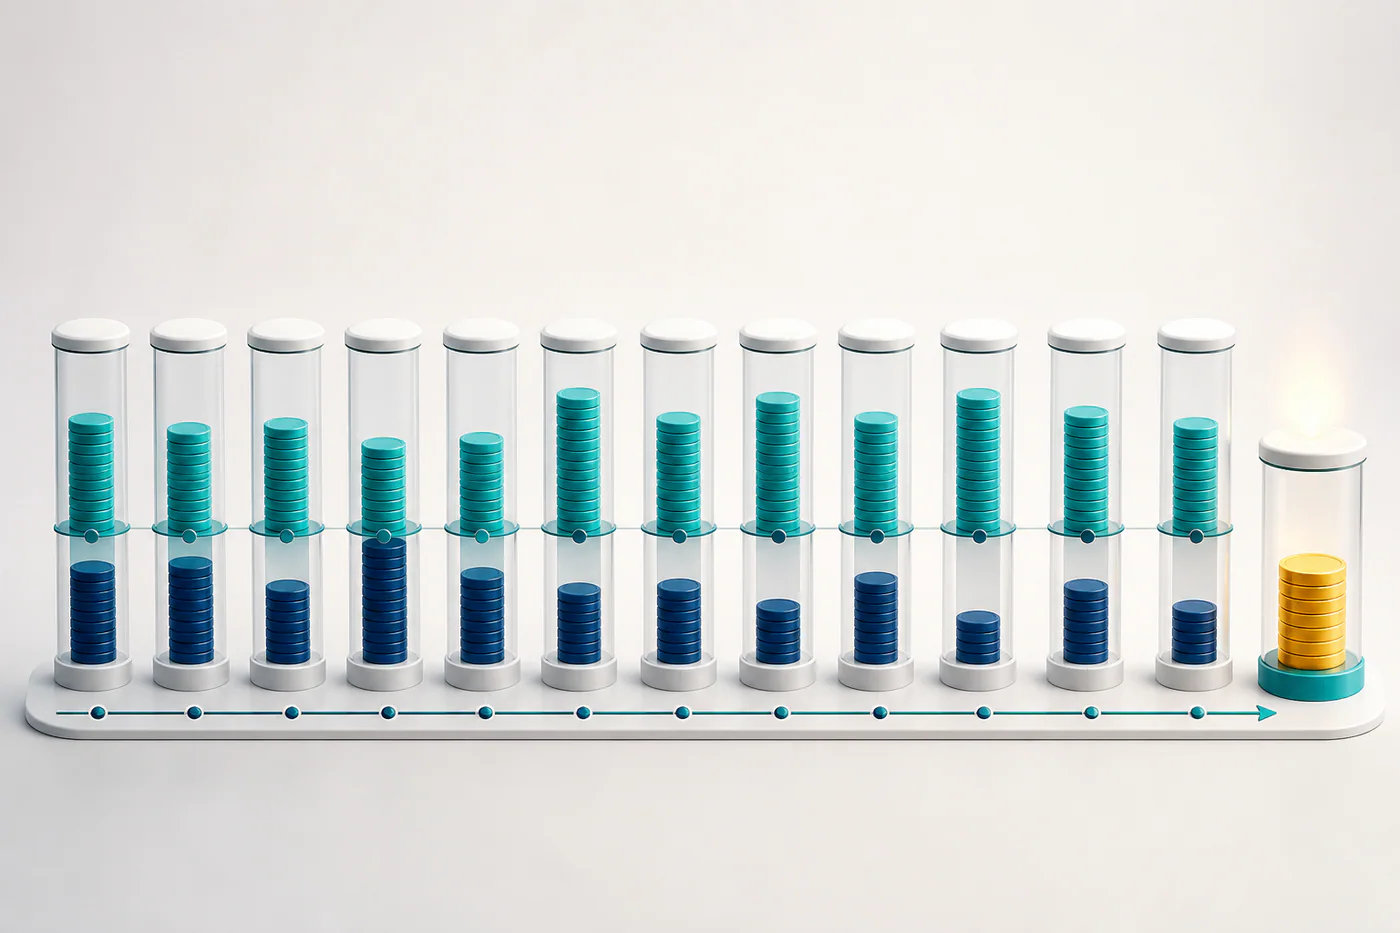
Calculate the weekly closing balance
For each week, add inflows to the opening cash and subtract outflows. The result becomes the next week’s opening balance. Add a minimum cash threshold that reflects the buffer your business needs to operate safely. A forecast can remain technically positive while still falling below a comfortable operating level.
The most valuable cells are often the first weeks in which cash approaches that threshold. They provide time to act before the bank balance becomes urgent.
Build three simple scenarios
Create a base case using the most realistic assumptions, a downside case with slower collections or lower sales, and an upside case for stronger receipts. Keep the changes understandable. A downside case might delay the largest customer payments by two weeks and reduce new cash sales by 15 percent.
Scenarios help you distinguish a temporary timing issue from a deeper funding need. They also show which assumption has the greatest effect, allowing management to focus attention where it matters.
Update the forecast every week
Replace estimates with actual results, roll the horizon forward by one week, and investigate significant differences. If a receipt arrived late, record why. If spending exceeded the plan, decide whether it was a one-time event or a new run rate. Forecast accuracy improves when the team learns from these variances rather than silently overwriting them.
Connect the process to invoicing discipline. Accurate invoices, clear payment terms, prompt reminders, and an up-to-date receivables aging report make incoming cash much easier to forecast.
Turn the numbers into actions
When the forecast identifies a shortfall, consider collecting deposits, accelerating approved invoices, negotiating supplier timing, reducing discretionary spending, adjusting inventory orders, or arranging finance early. Do not wait until the low-cash week to begin the conversation.
A 13-week forecast works because it is specific, frequent, and actionable. Keep the model simple enough to maintain, document the assumptions, and review it with the people who control sales, purchasing, and payments. The habit of looking ahead is more valuable than a complicated spreadsheet that no one updates.
Leave a Reply